
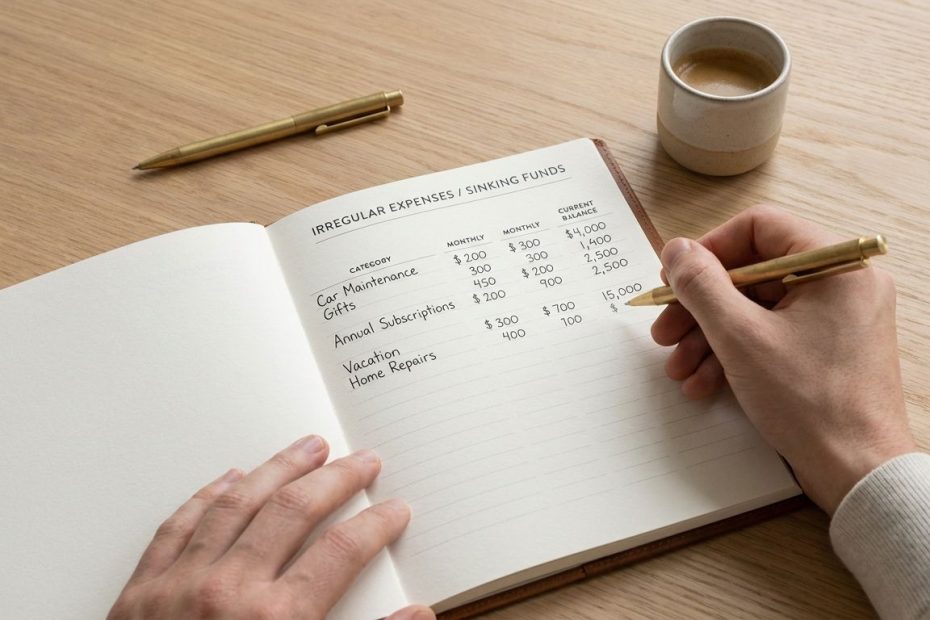
Irregular expenses stop wrecking your budget when you treat them like monthly bills before they arrive. The simplest system is to list the non-monthly costs you already know are coming, convert each one into a monthly amount, and fund those categories every single month.
If you want a budget that holds up in real life, this is the part that changes everything. You are going to see how to spot the expenses that keep blindsiding you, how to calculate the right monthly amount, and how to build a clean system that works without making your budget feel crowded or confusing.
What Are Irregular Expenses, And Why Do They Blow Up A Monthly Budget?
Irregular expenses are costs that show up on a schedule that does not match your paycheck cycle or your normal monthly bills. They are still predictable. Car repairs, annual insurance premiums, holiday gifts, school fees, home maintenance, medical deductibles, and subscription renewals all fit this category.
Your budget breaks down when you treat these costs like random bad luck instead of part of your normal spending pattern. You might handle rent, groceries, utilities, and debt payments with no issue, then lose control when tires, a vet bill, or a yearly membership fee hits. The expense feels sudden, but the real problem is that the money was never assigned ahead of time.
This is why so many people say they are “good at budgeting” and still feel financially unstable. What they usually mean is they can manage recurring monthly bills. That is not the same as managing total annual spending. Once you start looking at your money across the full year, these so-called surprise expenses stop being surprises and start becoming line items.
That shift matters because it changes your behavior. You stop relying on credit cards, stop raiding your grocery budget, and stop pretending next month will somehow be cheaper. You build a budget that reflects how your life actually works, not how a spreadsheet wishes it worked.
What Is The Simple Monthly Budget System For Irregular Expenses?
The system is straightforward: create sinking funds for non-monthly costs and contribute to them every month. A sinking fund is just money you set aside in advance for a specific future expense. You are not guessing your way through the month anymore. You are prepaying yourself for costs you know will arrive later.
Here is why this works so well. A traditional monthly budget only shows what is due right now. A sinking-fund budget shows what your life actually costs over time. When you divide annual or seasonal expenses into smaller monthly amounts, you smooth out the spikes that usually make one month feel easy and the next month feel like a disaster.
You do not need a complicated app or a dozen accounts to make this work. You need categories, realistic targets, and consistency. You can track these funds in a budgeting app, a spreadsheet, a notebook, or even a basic bank setup as long as each dollar has a job and you do not mix future-purpose money with general spending cash.
This system also removes the emotional drama from spending. When your car needs brakes and the money is already waiting in your car maintenance category, you are not panicking. You are executing the plan. That is what a solid budget is supposed to do.
How Do You Calculate The Right Monthly Amount For Each Expense?
The formula is simple: estimate the full cost, then divide it by twelve. If the bill is due sooner and you are starting late, divide by the number of months left until the due date. That gives you a clean monthly contribution target you can add to your budget right away.
Say your annual car insurance premium is $720. You would set aside $60 per month. If your holiday spending usually reaches $900, you would save $75 per month. If a subscription renews every six months at $120 and you are starting fresh right after the renewal, you would save $20 per month so the next payment is ready.
If you do not know what to put in a category yet, use your own transaction history. Pull the last year of bank and credit card statements and total up what you spent on gifts, repairs, travel, school costs, pet care, and other non-monthly categories. That gives you real numbers based on your life, which is far better than guessing from a generic template.
If your history is messy, start with a working estimate and refine it after a few months. The goal is not perfection in month one. The goal is to stop getting blindsided. Once you track the actual spending and adjust the monthly contribution, the system gets stronger fast.
What Sinking Funds Should You Set Up First?
You do not need twenty categories on day one. Start with the irregular expenses most likely to knock your budget off course. For most households, that means car maintenance, home maintenance, medical out-of-pocket costs, gifts, annual subscriptions, travel, and clothing or seasonal purchases.
Car expenses are one of the biggest budget disruptors because they arrive in uneven bursts. One month you spend almost nothing, then you need new tires, registration, a battery, or brake work. Homeowners deal with the same pattern at a larger scale. Plumbers, appliance replacements, yard equipment, minor repairs, and service visits rarely line up neatly with a monthly plan.
Medical costs also deserve their own category even if you have insurance. Copays, prescriptions, deductibles, dental work, vision costs, and urgent care visits can pile up fast. Gifts and holidays are another category people routinely underestimate, then overspend on during the busiest part of the year when cash flow is already tight.
Annual subscriptions are easy to forget because they are small until they stack up. A streaming renewal, warehouse membership, software plan, domain name, school fee, or roadside assistance plan may not look serious alone. Put them together, though, and you get a real monthly cost that belongs in your budget. Start with the categories that hit your life most often, then expand as your tracking improves.
How Much Should You Budget For Car And Home Costs?
For car maintenance and repairs, one practical method is to estimate based on how much you drive each year. American Automobile Association data lists maintenance, repair, and tires at 11.04 cents per mile. If you drive 12,000 miles annually, that works out to about $1,325 per year, or roughly $110 per month for that category alone.
If you prefer to use your own history, review the last twelve to twenty-four months of spending on oil changes, tires, batteries, brakes, inspections, repairs, and routine service. Add a buffer so one larger bill does not wipe out the fund. This method usually gives you a tighter number because it reflects your vehicle, driving habits, and local costs.
For home maintenance, a common planning rule is to set aside 1 percent to 4 percent of your home’s value each year. A home valued at $400,000 would translate to roughly $4,000 to $16,000 annually, depending on age, condition, and upkeep needs. At the low end, that is about $333 per month. Older homes or homes with aging systems usually justify a higher monthly target.
You do not have to fund every future home project at once. Focus on the real maintenance and repair pattern first. If you know larger replacements are approaching, you can create separate categories for roof, heating and air conditioning, appliance replacement, or exterior work. That gives you better visibility and stops one big project from draining your general maintenance fund.
Should Irregular Expenses Live Inside Your Budget Or Outside It?
They belong inside your monthly budget. If you keep irregular expenses outside the plan, you will keep treating them like exceptions, and your budget will keep failing at the exact moments you need it most. These costs are still part of your real spending. They just show up on a different timetable.
If you use a broad budgeting model like the 50/30/20 rule, your sinking funds still fit within it. Needs can include things like annual insurance, medical costs, home repairs, and car maintenance. Wants can include gifts, travel, entertainment renewals, and seasonal spending. Long-term replacement funds may sit closer to savings, depending on the purpose.
What matters is that you count the monthly contribution as the expense. That is where many people get confused. They save into a sinking fund and then feel like the actual purchase is a second hit to the budget. It is not. The purchase is simply the moment you use money you already reserved. Once you understand that, your budget becomes calmer and much easier to trust.
This also improves reporting. Your monthly spending may look more consistent because the budget is carrying the cost steadily rather than showing one giant spike whenever a bill arrives. That makes it easier to plan, easier to review, and much easier to stick with over time.
How Do You Keep The System Simple Without Creating Too Many Categories?
You keep it simple by organizing categories around how you actually spend, not around every tiny possibility. If separate categories help you stay disciplined, use them. If too many categories make you avoid the budget, group related costs under a smaller number of buckets with clear labels.
A clean setup might include Auto, Home, Medical, Gifts, Travel, Annual Bills, and Personal. Inside your budget notes or tracking sheet, you can list what each category covers. Auto might include tires, oil changes, registration, inspections, and repairs. Annual Bills might include membership renewals, software subscriptions, and yearly service plans.
You can also separate true emergencies from expected irregular expenses. A water heater replacement belongs in planning if you own a home and know systems wear out. A job loss fund belongs in your emergency savings. Keeping those functions separate prevents confusion and helps you avoid draining emergency cash for expenses that were always part of normal life.
The best system is the one you will review and fund every month. If you need fewer buckets, use fewer buckets. If you prefer detailed categories, build them. The structure matters less than the habit of assigning money before the expense arrives.
What Should You Do If You Are Starting Late Or Already Behind?
Start by listing the irregular expenses most likely to hit within the next six to twelve months. Prioritize the ones with a fixed due date or the highest probability of landing soon. Annual insurance, school costs, holidays, car registration, and known maintenance needs should move to the top of the list.
Then calculate how many months remain before each expense is due and divide the expected cost by that number. This will give you a catch-up contribution amount. Some categories may need a temporary heavier contribution for a few months. That is normal. You are building the system after the fact, so the first phase is always a little tighter.
If your cash flow cannot support full funding for every category right away, rank them. Fund essential and time-sensitive expenses first, then add the lower-risk categories as margin opens up. You do not need to do this perfectly to get real benefit. Even partial pre-funding can reduce the damage of an upcoming bill.
Keep the categories active once you catch up. A lot of people scramble to cover a yearly expense, pay it, then stop funding it until the next due date appears on the calendar again. That resets the problem. The monthly contribution only works when it stays in the budget every month, whether the bill is near or far away.
What Is The Best Way To Budget For Irregular Expenses?
- List your non-monthly expenses.
- Estimate each yearly total.
- Divide each by twelve.
- Fund those sinking funds every month.
- Spend from the category when the bill arrives.
Build A Budget That Can Handle Real Life
If you want a budget that keeps working past payday, you need to fund irregular expenses before they hit. That one change turns surprise bills into planned spending, reduces credit card dependence, and gives you a steadier month-to-month cash flow. You do not need a complicated system, just clear categories, realistic monthly targets, and the discipline to keep funding them. Once you start treating annual, seasonal, and repair costs like monthly obligations, your budget becomes more accurate and a lot less stressful. Keep refining the numbers, keep the categories visible, and your money plan will start matching real life instead of breaking every time life gets normal.
References:
- https://www.ynab.com/blog/how-to-embrace-your-true-expenses
- https://www.ynab.com/blog/non-monthly-expenses-for-your-budget
- https://www.reddit.com/r/personalfinance/comments/mq7heq
- https://www.reddit.com/r/actualbudgeting/comments/1su7ghi/how_do_you_handle_sinking_funds_for_stuff_thats_6/
- https://www.reddit.com/r/ynab/comments/14e9wts/budgeting_for_irregular_expenses/
- https://www.reddit.com/r/personalfinance/comments/12t3deq
- https://newsroom.aaa.com/wp-content/uploads/2025/09/UPDATE-AAA-Fact-Sheet-Your-Driving-Cost-9.2025-1.pdf
- https://www.reddit.com/r/Frugal/comments/1pjyp6n/how_do_you_plan_for_irregular_expenses_so_they/
- https://www.bobvila.com/articles/how-much-to-budget-for-home-maintenance/
- https://www.ramseysolutions.com/budgeting/50-20-30-budget-rule
- https://www.reddit.com/r/budget/comments/1qfrwsi/sinking_funds_still_counting_as_expenses_new_to/

Brian C Jensen is the CEO of Legacy Global Consulting, Inc., a management consulting firm. With 10+ years of experience, he advises organizations on digital transformation, risk management, and growth strategy—helping clients anticipate market shifts and scale sustainably.